Competition Bureau investigates minimum advertised pricing policies in grocery sector
Canadian Press
The Competition Bureau is investigating minimum advertised pricing policies in Canada’s grocery sector, examining whether the practice makes discounts harder to find and weakens price competition. CAMP Executive Director Keldon Bester told The Canadian Press the policies can soften competitive price signals and lead to more uniform pricing.

CAMP welcomes legally binding Empire property controls agreement, calls for broader action across grocery sector
September 22, 2026 [Ottawa, ON] – The Canadian Anti-Monopoly Project (CAMP) welcomes a new legally binding agreement between the Competition Bureau and Empire Company Limited addressing the grocery giant’s use of property controls, while emphasizing that barriers to competition extend beyond one company and beyond the grocery sector.
The Competition Bureau announced today that Empire, the parent company of Sobeys, Farm Boy, Safeway, IGA, Foodland, FreshCo and other grocery banners, has formalized commitments it first announced in July through a consent agreement registered with the Competition Tribunal. Unlike the company’s earlier voluntary commitments, the agreement is legally binding and enforceable, with the force and effect of a court order.
“In July, we said scrutiny was paying off but voluntary commitments needed accountability. Today, those commitments have teeth,” said Keldon Bester, Executive Director of the Canadian Anti-Monopoly Project. “This is a meaningful step toward opening local grocery markets to more competition and shows the value of sustained enforcement when companies control the terms on which competitors can enter a market.”
Under the agreement, Empire cannot enforce existing restrictive covenants, create new ones or ask others to establish restrictive covenants that benefit the company. It must also limit its use of exclusivity clauses, including restrictions affecting specialty food retailers and radius clauses that prevent food retailers from operating near Empire grocery developments. The agreement also prevents Empire from enforcing existing exclusivity clauses in 19 local markets identified by the consent agreement.
The agreement follows several years of Competition Bureau scrutiny of property controls. The Bureau’s 2023 grocery market study concluded that these restrictions can prevent new grocers from entering markets and deny consumers the benefits of greater competition. Its investigation into property controls used by other grocers remains ongoing.
“This agreement is progress, but the grocery competition problem is bigger than Empire,” Bester said. “The Bureau’s ongoing work across the sector matters, as does action by provinces to prevent property controls from unnecessarily shutting competitors out of local markets.”
“And the lesson here is bigger than grocery. Across the economy, Canadians benefit when businesses can enter markets and compete without unnecessary contractual or structural barriers standing in their way. Enforcement that removes those barriers is an important part of building more competitive markets.”
Earlier this month, the Competition Bureau reported that Empire, Loblaw and Walmart had all taken steps toward eliminating property controls, while noting that it continues to investigate the practices of major grocery retailers and assess their effects on competition.
Canada, EU Deepen Ties But Diverge on Consumer Protection
Do Not Pass Go
In Do Not Pass Go, Peter Nowak examines the widening gap between Canada and Europe on consumer protection, from click-to-cancel rules and telecom complaints to airline passenger rights. Keldon Bester, Executive Director of the Canadian Anti-Monopoly Project, argues that stronger consumer protection should be part of Canada’s competition and economic sovereignty agenda. As Canada deepens its relationship with Europe, he points to the EU’s stronger approach to consumer rights as an example of how governments can make markets work better for people.
CAMP statement on U.S. Google ad tech remedies decision
September 17, 2026 [Ottawa, ON] – A U.S. federal court has rejected the Department of Justice’s request to break up parts of Google’s online advertising business after finding that the company illegally acquired and maintained monopoly power in the publisher ad server and ad exchange markets. Instead, the court will rely on behavioural remedies that require Google to make its products work more easily with rivals, share more data with publishers and follow new rules against discriminatory conduct.
The decision leaves Google in control of both DFP, the publisher ad server at the centre of the case, and AdX, its ad exchange. The court had previously found that Google unlawfully tied the two products together and used that integration to shut out competitors and protect its monopoly.
“This is a missed opportunity to change the structure that allowed Google to build and protect its monopoly in the first place,” said Keldon Bester, Executive Director of the Canadian Anti-Monopoly Project. “The court found that Google used the connections between its products to shut out competitors and strengthen its position. The remedy now asks Google to keep that structure and follow a new set of rules inside it.”
The court found that DFP served 91 per cent of worldwide open-web display impressions in the publisher ad server market in 2022. AdX handled up to 71 per cent of transactions among the exchanges that produced data in the case, and Google maintained a 20 per cent AdX take rate for more than a decade even as rival exchanges often charged less. The court also found that publishers had little choice but to continue using AdX.
The Competition Bureau is pursuing its own case against Google in Canada. It alleges that Google abused its dominant position across the online advertising technology supply chain and is asking the Competition Tribunal to order Google to sell DFP and AdX, along with other measures aimed at the conduct the Bureau says harmed competition.
“Canada should learn from the U.S. decision, not copy it,” Bester said. “Interoperability, data access and rules against self-preferencing can help, but the Bureau should keep making the case for structural change. If one company still controls the tools publishers use to sell ads and the marketplace where those ads are sold, the underlying conflict remains.”
Europe is the next major jurisdiction expected to decide how to address Google’s conduct in online advertising. Whatever remedy emerges there, Canada should make its own assessment of what is needed to restore competition in the Canadian market. The Competition Bureau and Competition Tribunal should focus on whether the final remedy reduces Google’s ability to favour its own products, lowers barriers for competitors and gives Canadian publishers and advertisers meaningful alternatives.
Competition in Canada's Food Supply Chain
Canada’s food supply chain is shaped by concentrated markets at nearly every stage, from seeds and equipment to processing, transportation, distribution and grocery retail. In its submission to the Competition Bureau’s examination of competition in the food supply chain, CAMP argues that this concentration deserves closer scrutiny because it affects both the prices producers receive and the prices Canadians ultimately pay for food.
CAMP calls on the Bureau to examine how market power operates across the full chain, including consolidation in processing and equipment dealerships, access to rail and distribution infrastructure, the dependence of independent grocers on competitors’ wholesale networks, and pricing and exclusive dealing practices at the retail level. The submission also urges the Bureau to use lessons from past mergers and acquisitions to better understand how consolidation has shaped competition over time.
Check out CAMP’s full submission here.
EU Leading the Way on Cloud Computing Regulation
- The European Commission has announced its preliminary position that two major cloud computing providers, Amazon Web Services and Microsoft Azure, are gatekeepers under the Digital Markets Act, the EU’s digital competition law.
- Gatekeeper designation imposes interoperability and portability obligations on designated suppliers, meaning the companies would be obliged to make their services compatible with a wider array of vendors, allowing clients to more easily deploy technologies on multiple providers’ infrastructures.
- Canada faces similar issues in the cloud computing space. As CAMP lays out in its Parting Clouds report, a strategy based on procurement, utility-like regulation, and competition enforcement can restore competition to the cloud market.
In June of 2026, the European Commission announced its preliminary position that cloud computing services Amazon Web Service (AWS) and Microsoft Azure should be designated as “gatekeepers” under their Digital Market Act (DMA). The application of the DMA to cloud computing would be a major shift in how Europe’s market for digital infrastructure works, and the ability of the biggest players to apply their market power. The designation is not final: Amazon and Microsoft can respond to the Commission’s preliminary findings in September before it concludes its investigation, which it aims to do by November 2026; if designated, the companies would then have six months to bring AWS and Azure into compliance with the DMA.
What does Gatekeeper Status under the Digital Markets Act mean?
The Digital Markets Act (DMA) is the European Union’s competition regime for the digital economy, aimed at keeping European markets fair and contestable not only for businesses in the technology sector, but for all the businesses who rely on technology services and platforms to operate and reach consumers. To do this, the DMA imposes obligations on specific products and services that are intended to ensure their conduct in the market is fair and does not impede competition. Gatekeeper status applies to “core platform services,” digital systems and technologies that have become fundamental to the ways that people use the internet to access media, products, and services. These systems include social networking and content sharing platforms, internet browsers, operating systems and online marketplaces.
The DMA is complementary to national competition laws, and covers many of the same activities, but with a crucial difference. Instead of case-by-case competition investigations after potentially anticompetitive conduct has occurred, the DMA imposes up-front obligations on designated gatekeepers. Most competition law is reactive: enforcement must connect anticompetitive activities to established dominance, delineated markets and measurable harms. Gatekeeper status establishes market dominance and prohibits certain activities regardless of rationale and effect. Importantly, it puts the compliance responsibility on the gatekeepers themselves.
Gatekeepers are defined by their scale in terms of users and revenue, and their economic importance. Cloud computing services are different than other platforms covered under the DMA since their end users aren’t typically consumers but organizations like businesses and governments. Therefore, the potential application to cloud computing is novel and wholly appropriate given the role that cloud providers play in the digital economy.
The Commission reached their preliminary position based the impact of the company on the EU’s market economy, the importance of the system for connecting businesses to end users, and the entrenchment of those companies’ market positions. By these measures, applying the DMA to cloud computing is straightforward. Businesses and governments depend on these services as key infrastructure to store, access, and use their data, and to deploy software. While the absolute number of direct business clients might not be very large, businesses and governments rely on cloud infrastructure to serve hundreds of millions of users. When AWS or Azure go down unexpectedly, millions of users lose access, losses can total in the billions, and entire sectors of the digital economy grind to a halt.
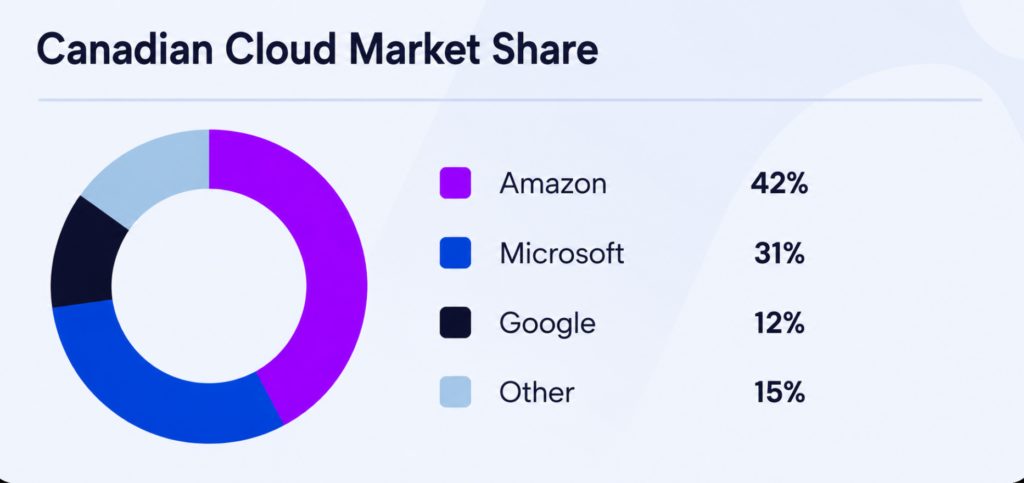
As for entrenchment, AWS, Azure and Google Cloud have over 70% of the cloud infrastructure market in Canada and Europe. Governments and businesses find themselves locked into proprietary ecosystems, long duration contracts, and high costs for switching services between providers.
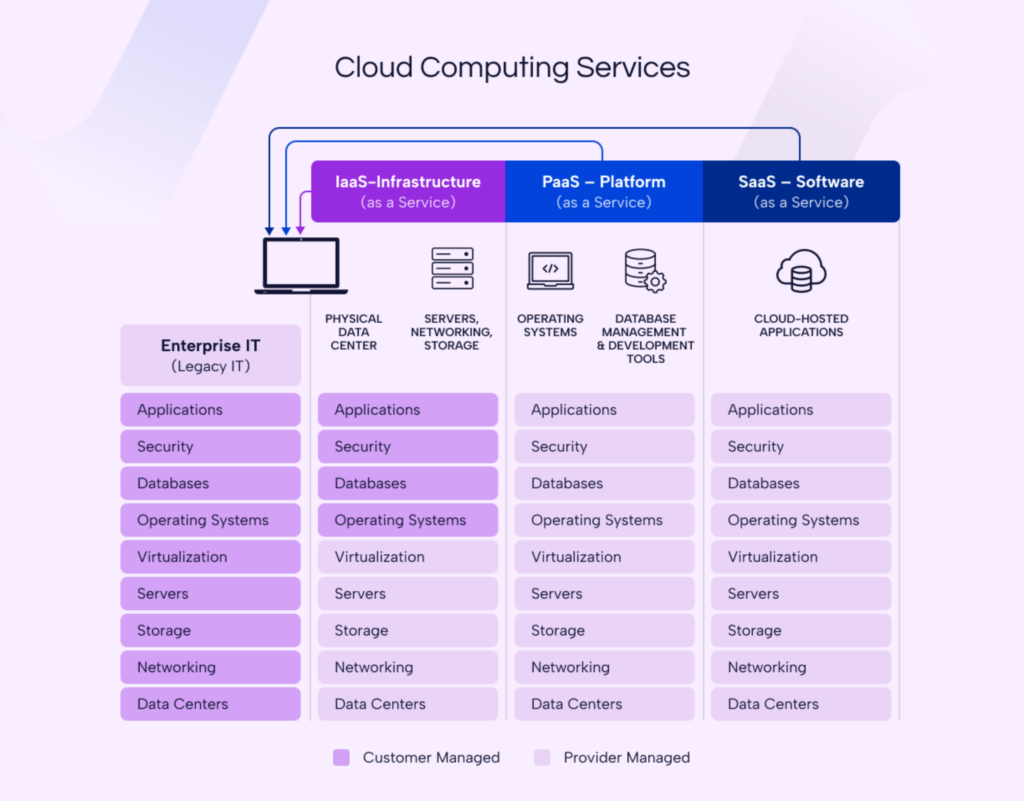
Making cloud providers gatekeepers aims to address what competition regulators have consistently identified as major problems in the market, namely, the vendor lock-in that makes it difficult for clients to access the benefits of what competition there is in the market. As is the case in many markets, lowering switching costs is one of the most direct paths to increasing customer choice and restoring competition to the market.
To this end, gatekeepers are required to make services interoperable, so that the friction of changing providers is minimized, and customers have more choices for vendors and tech. Cloud providers would also need to make it easier for clients to export and move their down, known as portability.
Alongside technical changes, gatekeeper status could affect contract clauses that tie the use of one proprietary service to another. The DMA also prohibits self-preferencing, when companies promote their own products above their competitors in a marketplace they control. Since infrastructure providers like AWS and Azure also control marketplaces where companies search for and integrate technologies into their workflows, they have potential line of sight into each piece of technology running on their cloud products, and potentially competing with other lines of business. The DMA prohibits them from using their control over the market to make their products easier to find and install than their competitors.
Why does this matter to Canada?
AWS and Microsoft will likely contest the designation, but if it is upheld, they will have six months to come into compliance with the DMA. Regardless of the outcome, the move signals that the European Commission has made the connection between cloud computing and their goal of promoting competition across digital markets.
As market share data shows, Canada’s situation is similar, and possibly even more intense than Europe’s. In both cases, public and private sector businesses are heavily invested in US cloud providers and have similar growing concerns about how this reliance can be turned into economic leverage. But a decisive break with US cloud providers is not realistic as a short-term proposition. Contracts are long, migration is a major undertaking, and high barriers to entry mean alternatives are lacking. The EU has a smattering of cloud providers, Canada fewer, and none offer services at the same scale or reach as the hyperscalers. Years of dominance and investing in scalability has entrenched their position. Mending the market means giving competitors the means to compete and grow. By making it easier to switch providers, competitors will be ready to move when their potential clients are.
Canada can start now to make its public and private sector less dependent on big tech Infrastructure. In our Parting Clouds report, CAMP lays out a three part strategy to lessen dependence on hyperscalers and free up competition in cloud computing.
First, the government should use its buying power in procurement to break vendor dependence. Interoperability and portability requirements in Europe will require providers to develop and adapt to comply. Canada’s governments can build requirements for the same technologies and capacities into their own cloud contracts.
Second, legislation is needed to ensure that the same terms are available for private businesses. This could mean regulating the cloud like a utility, similar to railroads, electricity, and telecommunications. Codes of conduct that target self-preferencing, price discrimination, and punitive egress fees can restore competitive pressures to the market and benefit all customers.
Finally, Canada can make sure our competition authorities have the means and the mandate to investigate abuse of dominance in the cloud market. The Competition Bureau has market study powers and could build off the cases of other regulators who have identified anticompetitive practices like self-preferencing, licensing abuses, and bundling and tying that abuse market dominance and suppress innovation in our technology sector.
These are just the first steps to breaking with the hyperscalers, but they have the potential to alter competitive dynamics in the market for cloud computing. Interoperability and portability create the space for smaller, specialized, and domestic competitors to contest the dominance of the cloud giants in important niches before expanding their offerings.
Canada should be watching the European Commission’s designation process carefully, but we should not wait to act. The EU has correctly identified the components of a competitive and fair computing market for computing infrastructure.